While doing chores one hot afternoon in Phnom Penh, I decided to watch The Big Short, a film that chronicles the gross negligence that fueled the 2008 financial crisis. I scrubbed clothes in a basin and washed my dishes as an all-star cast of men yelled angrily into Blackberries between b-roll cuts of houses and envelopes stamped “eviction notice.” It was a delightful way to pass the hottest part of the day.
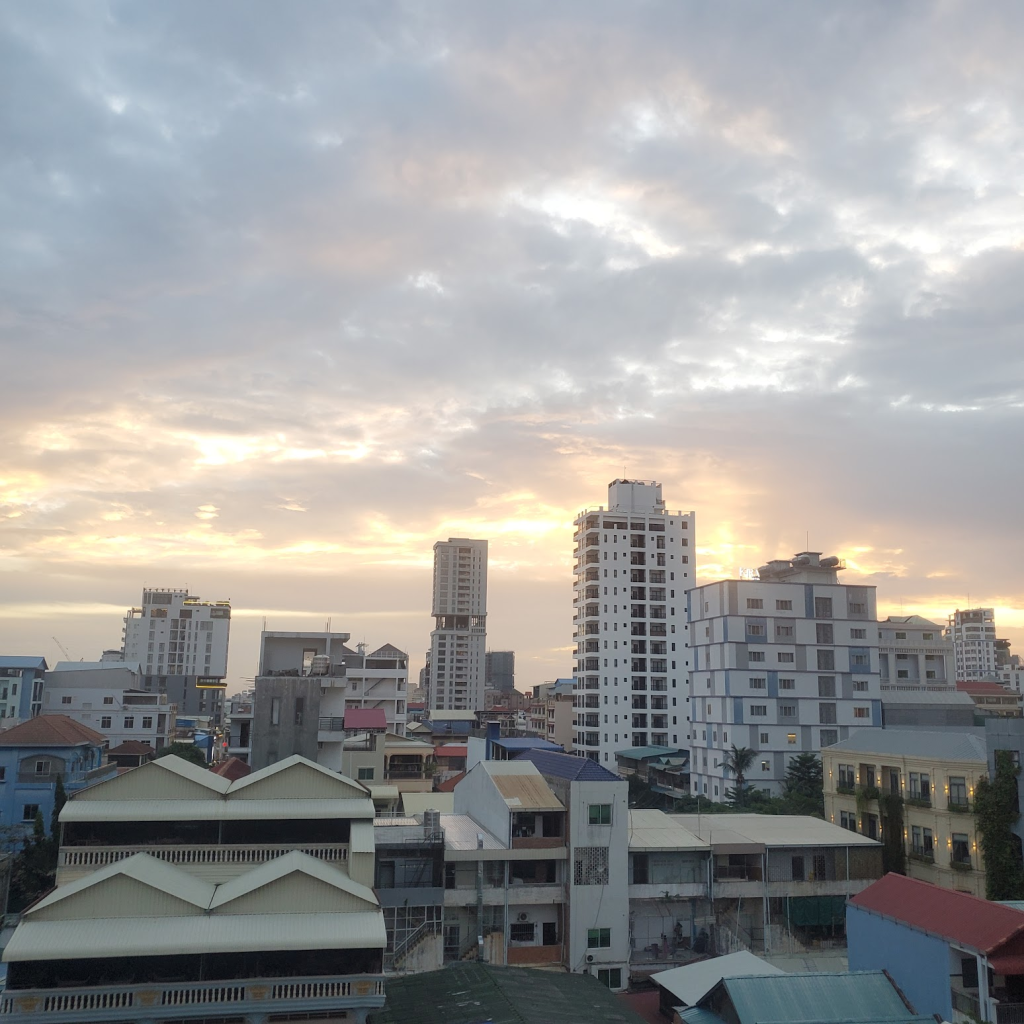
At one point, I left my air-conditioned room to hang my laundry on the balcony. Opening the door, I was blasted by sticky Cambodian heat. Something about that strong, humid gust — with its peppery smell of gasoline and rain-patched asphalt — brought me back a decade. Suddenly, I was back in Texas, stepping out onto the smoldering porch to hang wet clothes in the sun. Texas: the place my family ended up as a result of the financial crisis at the center of the very movie I was now watching. Funny how a single sensation can make time fold.
Trying vainly to shake off the mild shock of memory, I returned to my movie. At some later point, Brad Pitt’s character highlighted the human cost of financial disaster: “People lose homes. People lose jobs. People lose retirement savings, people lose pensions. You know what I hate about […] banking? It reduces people to numbers.”
That line touched my mind like a live wire. Suddenly, I was immersed in thoughts about my internship, specifically about the complaint LICADHO jointly filed to the International Financial Corporation (IFC) on behalf of Cambodian microfinance borrowers. Cambodia has the world’s highest per-capita microfinance debt. The average “micro”loan in Cambodia exceeds 4,000 USD$, far outstripping the average rural family’s yearly income of around 1,400 USD$.1
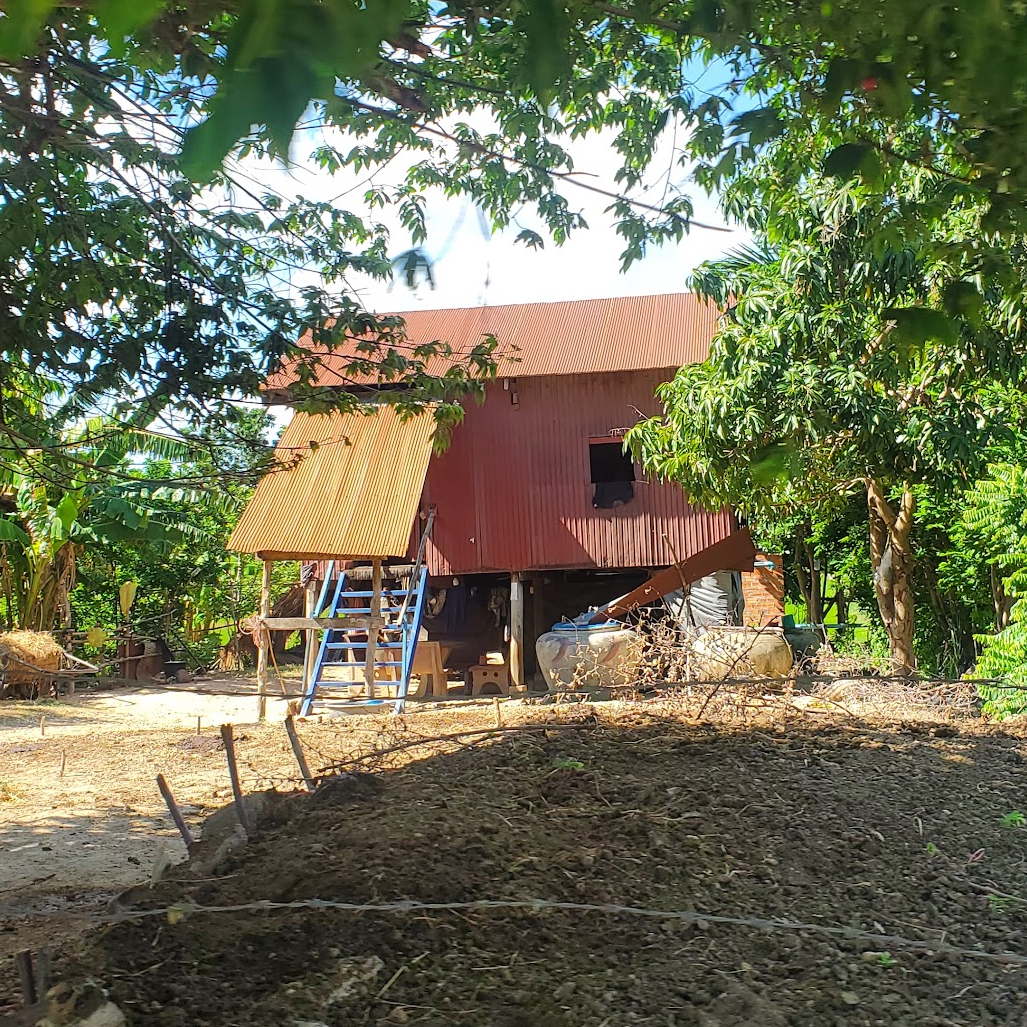
But those numbers say nothing of the crushing cost of high debt. In Cambodia, 80% of the population lives in rural areas.2 Despite this, microfinance institutions routinely take their land title — their primary asset and source of livelihood — as collateral, without sufficiently inquiring into families’ ability to repay.3 When families inevitably experience a crop failure or an emergency, they fall behind on their payments. Threats, harassment, and coerced sale of family land soon follow. LICADHO’s complaint and the IFC’s ombudsman’s investigation both documented the enormous human toll of these predatory practices: food insecurity, children forced out of school and into work, loss of communal Indigenous land, even suicides.4 For years now, Cambodia has been undergoing its own financial crisis, largely in silence.
I snapped back to the movie just in time to hear Steve Carell’s character curse the financial institutions that perpetuated the collapse: “They weren’t being stupid, they just didn’t care.”
And suddenly, I was crying — crying so hard I could barely read the end screen explaining that six million people lost their homes in the crash. My family’s own financial collapse was in those statistics. My parents’ jobs, our house, our car: all of that loss was tallied up and logged somewhere. When we had nothing left to lose, we went to Texas to start over. We moved houses and changed schools half a dozen times, constantly uprooting ourselves as my parents worked to rebuild our lives. It was a rough chapter in my life.
But at least I had school. At least I had a place to call home. At least my parents could find decent work and provide for us. We didn’t go hungry. There was stress and arguments and so much shame, but my family was ultimately alright. And while it sucks that there was (almost) no accountability for the people who caused it, at least there was a little bit of reform. At least someone collected some statistics. At least someone made a movie about it all. In some small way, we counted.
Cambodian borrowers are not so lucky. Rejecting its own ombudsman’s findings, the IFC decided in June that its Environmental and Social Sustainability (E&S) policies do not apply to microfinance borrowers.5 This decision cuts borrowers off from one of the few accountability mechanisms that could give them any relief. Instead of taking responsibility, the IFC reiterated the importance of domestic accountability mechanisms despite the risks of reprisal, the lack of judicial independence, and the enormous barriers to securing meaningful change to the regulatory environment from within Cambodia.
In other words, Cambodian borrowers have been left to fend for themselves. Their losses will not count. Yet again, a major institution has decided to turn a blind eye to the pain that its investment products inflict on real people.
Obviously these crises are different, and the suffering cannot be compared. But sitting in my Phnom Penh apartment while the credits rolled, I couldn’t help the tears; the underlying ethos just felt too familiar.
They weren’t stupid. They just didn’t care.
By: Chanel Perreault
- “Right to Relief: Indebted Land Communities Speak Out”, LICAHDO and Equitable Cambodia, June 2021, available at: https://www.licadho-cambodia.org/reports/files/234Report-RightToRelief-2021-en.pdf. ↩︎
- “Cambodia”, UNDP, available at: https://www.adaptation-undp.org/explore/asia-and-pacific/cambodia ↩︎
- Right to Relief, supra, note 1. ↩︎
- Right to Relief, supra, note 1; “Compliance Investigation Report Regarding IFC’s Exposure to Financial Institutions in Cambodia (ACLEDA, Amret, Hattha Bank, LOLC, PRASAC, and Sathapana)”, CAO, 10 Oct 2025, available at: https://www.cao-ombudsman.org/sites/default/files/downloads/CAO-InvestigationReport-CambodiaFI04-Oct102025-ENG.pdf ↩︎
- “Statement from IFC Board on the CAO Investigation Report on Cambodia Microfinance”, IFC, 24 June 2026, available at: https://www.ifc.org/en/statements/2026/ifc-board-statementon-cao-investigation-report-on-cambodia-microfinance ; “Management Report in Relation to the CAO Compliance Investigation Report on ACLEDA, AMhert, HTB, Prasac, LOLC, and Sathapana”, IFC, 5 February 2026, available at: https://www.cao-ombudsman.org/sites/default/files/downloads/IFC-ManagementReport-CambodiaFI04-Feb052026-ENG_0.pdf. In rejecting the CAO’s reportand instead embracing the IFC’s Management Report, the IFC board accepted the claim that harms suffered by microfinance borrowers fall outside the scope of their E&S policies and thus its mechanism of recourse. ↩︎